Our archives on credit risk
Datafiles May 20

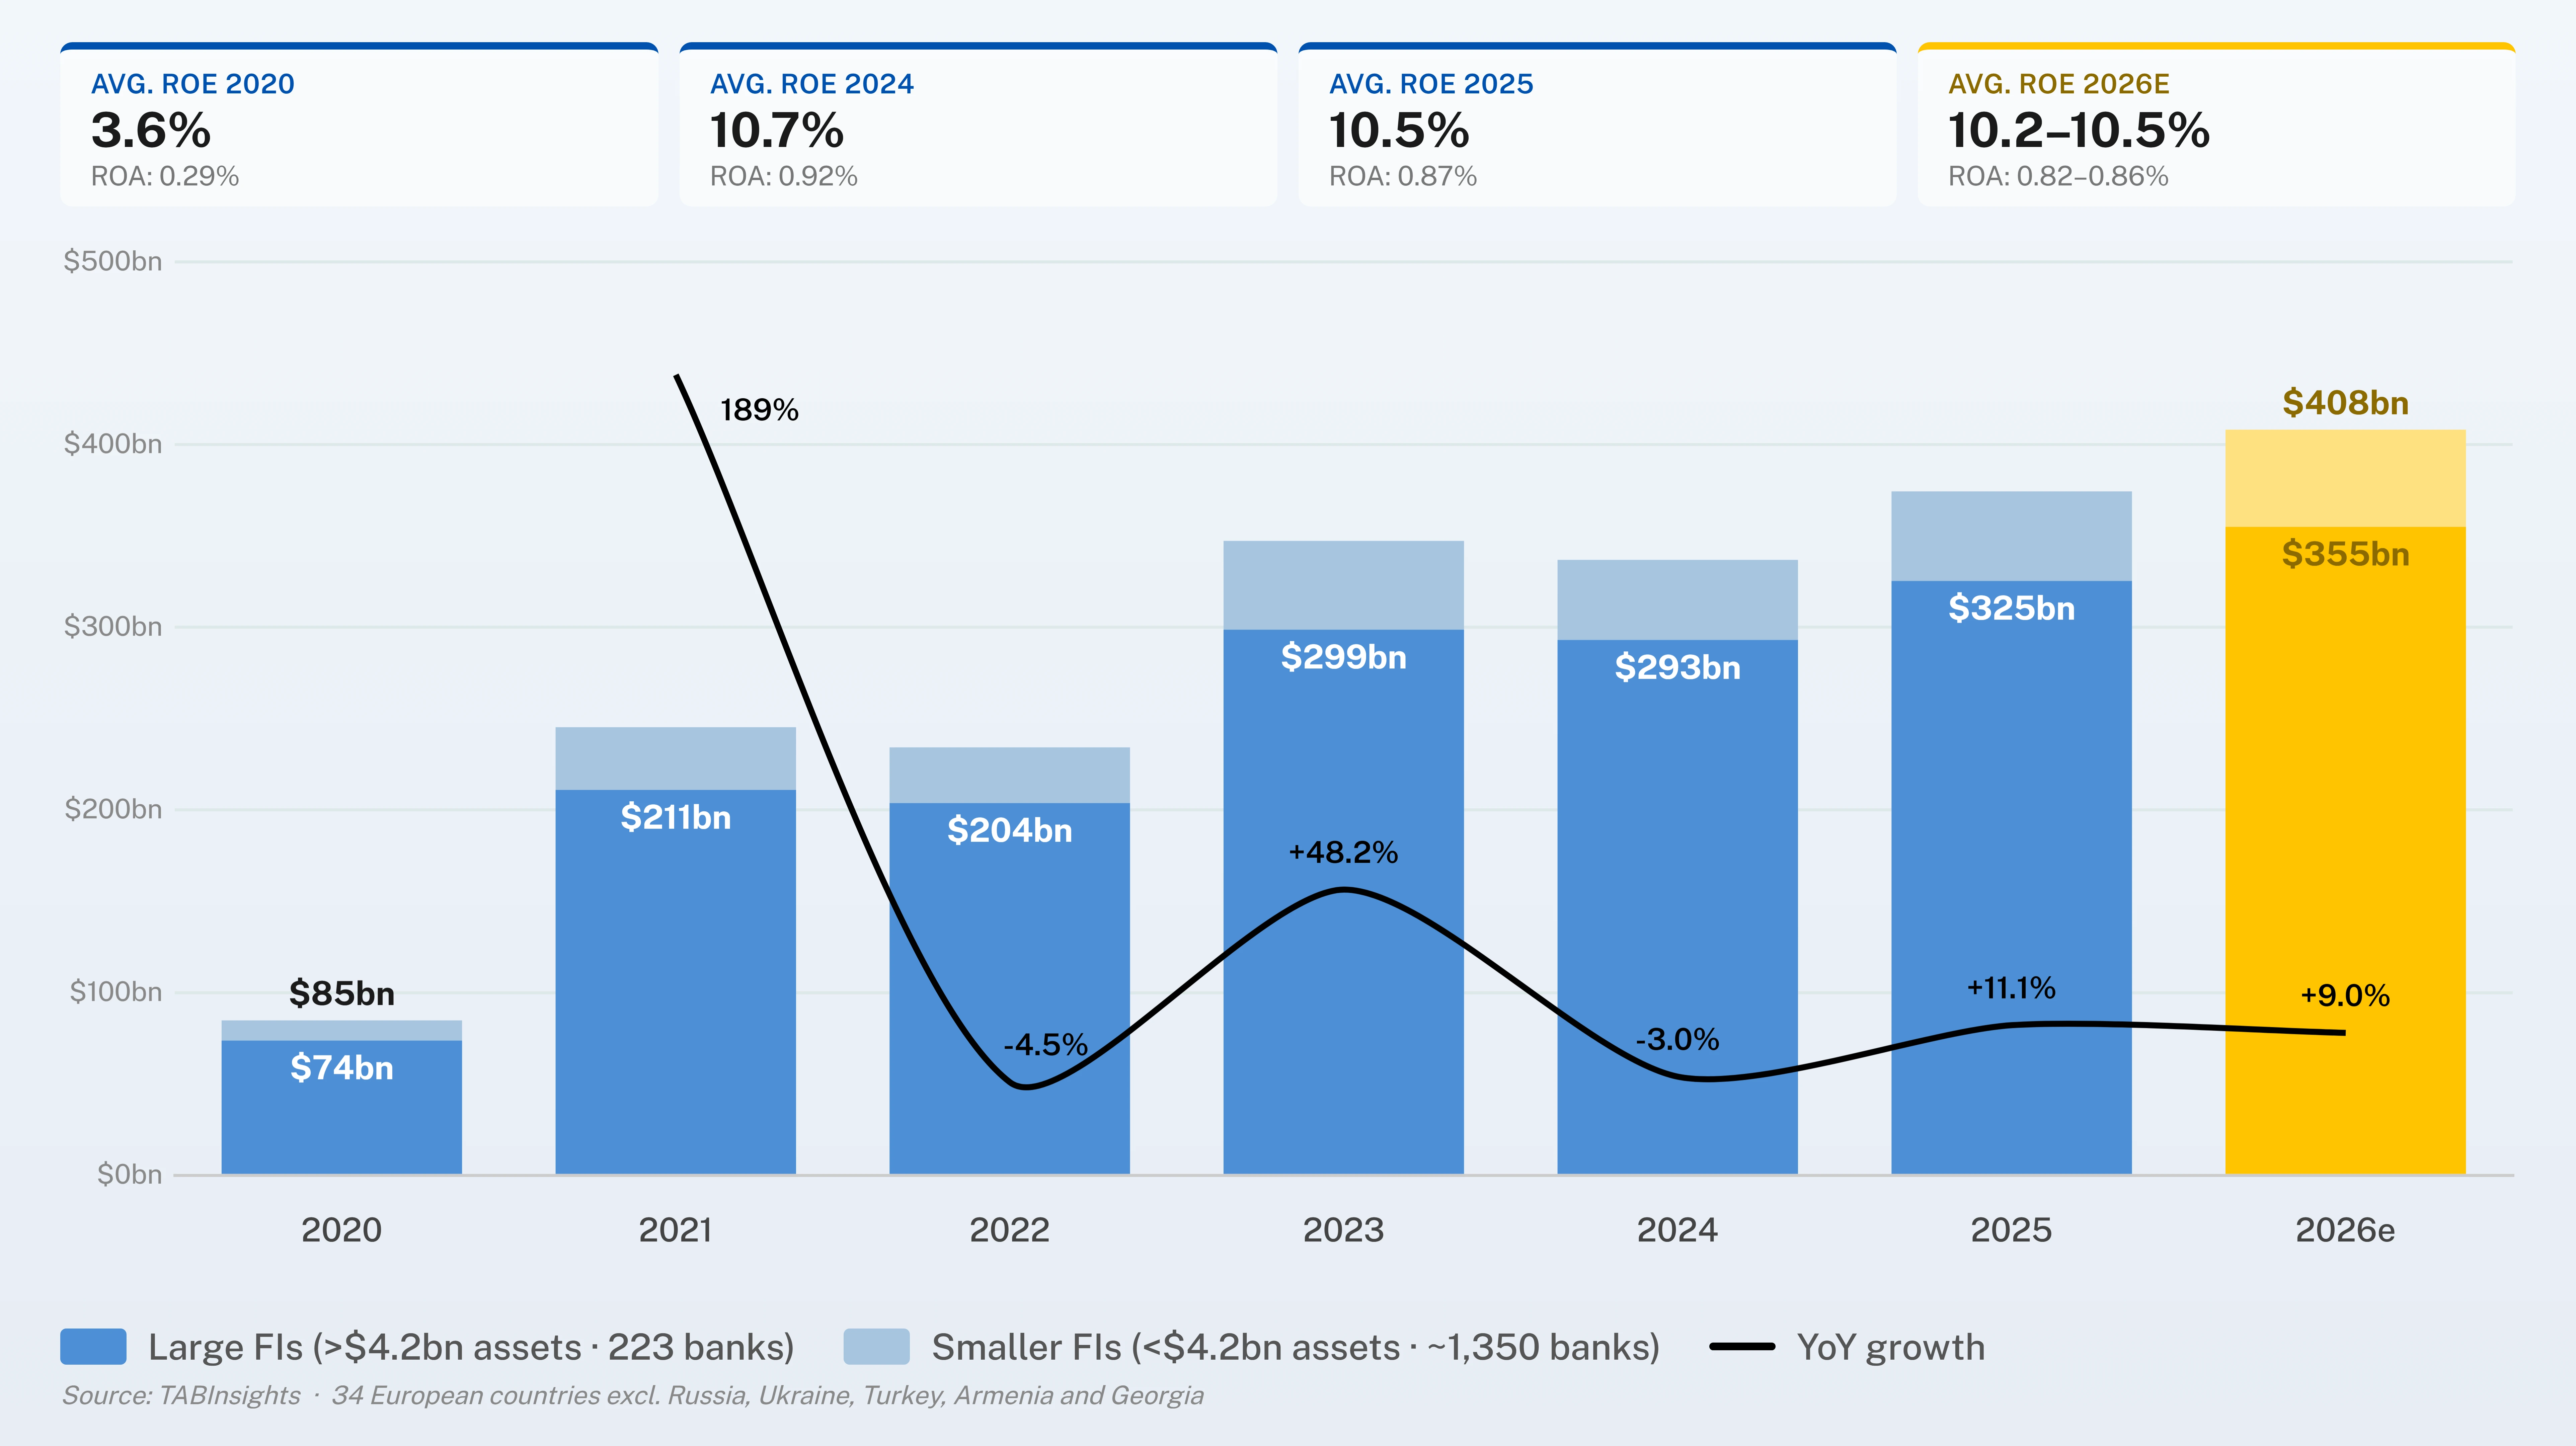
European banks across 34 markets saw net profit grow by a factor of 4.4 between FY2020 and FY2025, driven by post-pandemic recovery and the European Central Bank’s (ECB’s) most aggressive rate-hike cycle in a generation between 2022 and 2023. As these growth tailwinds ease and the International Monetary Fund (IMF) and ECB revise Euro area real GDP growth to between 0.9 and 1.1% in 2026, banks that built structural capacity during the windfall years now demonstrate more stable earnings, with banks in Belgium, Eastern Europe and the Nordics emerging as structural leaders.

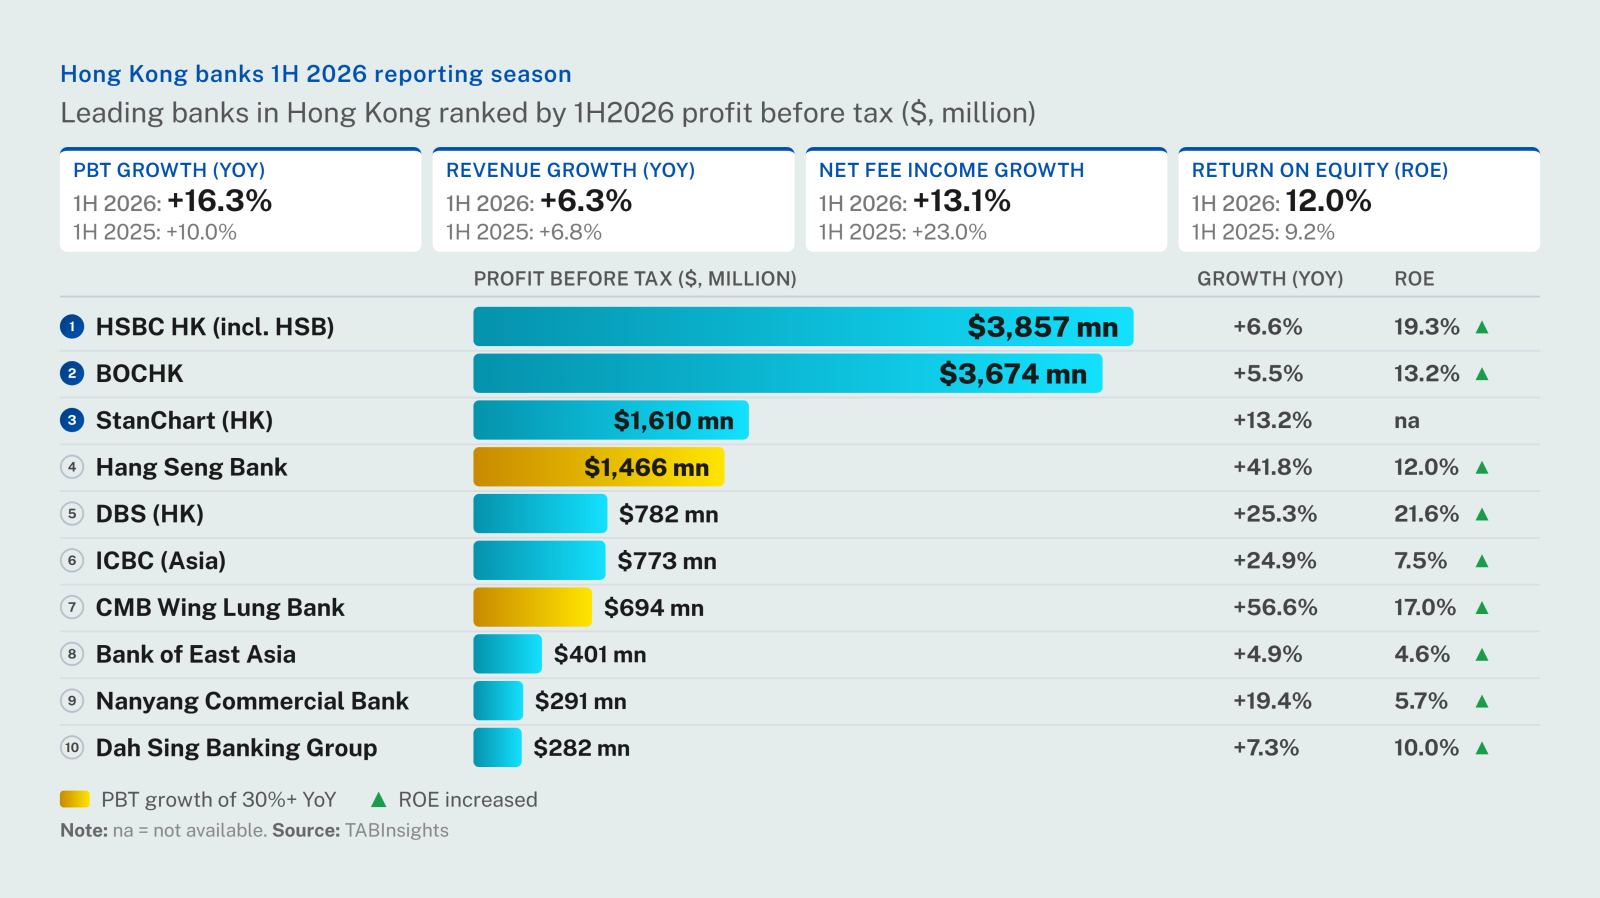
Hong Kong’s leading banks accelerated median pre-tax profit growth to 16.3% year on year (YOY) in the first half of 2026 (1H2026). HSBC Hong Kong (including Hang Seng Bank) continued to lead the large-scale bank segment in earnings scale and returns, while DBS Hong Kong and CMB Wing Lung Bank delivered stronger growth momentum and profitability among mid-sized banks. Across the sector, growth was increasingly supported by fee-based businesses, wealth management, cross-border activity and digitally-enabled customer engagement, which emerged as key drivers of revenue expansion.

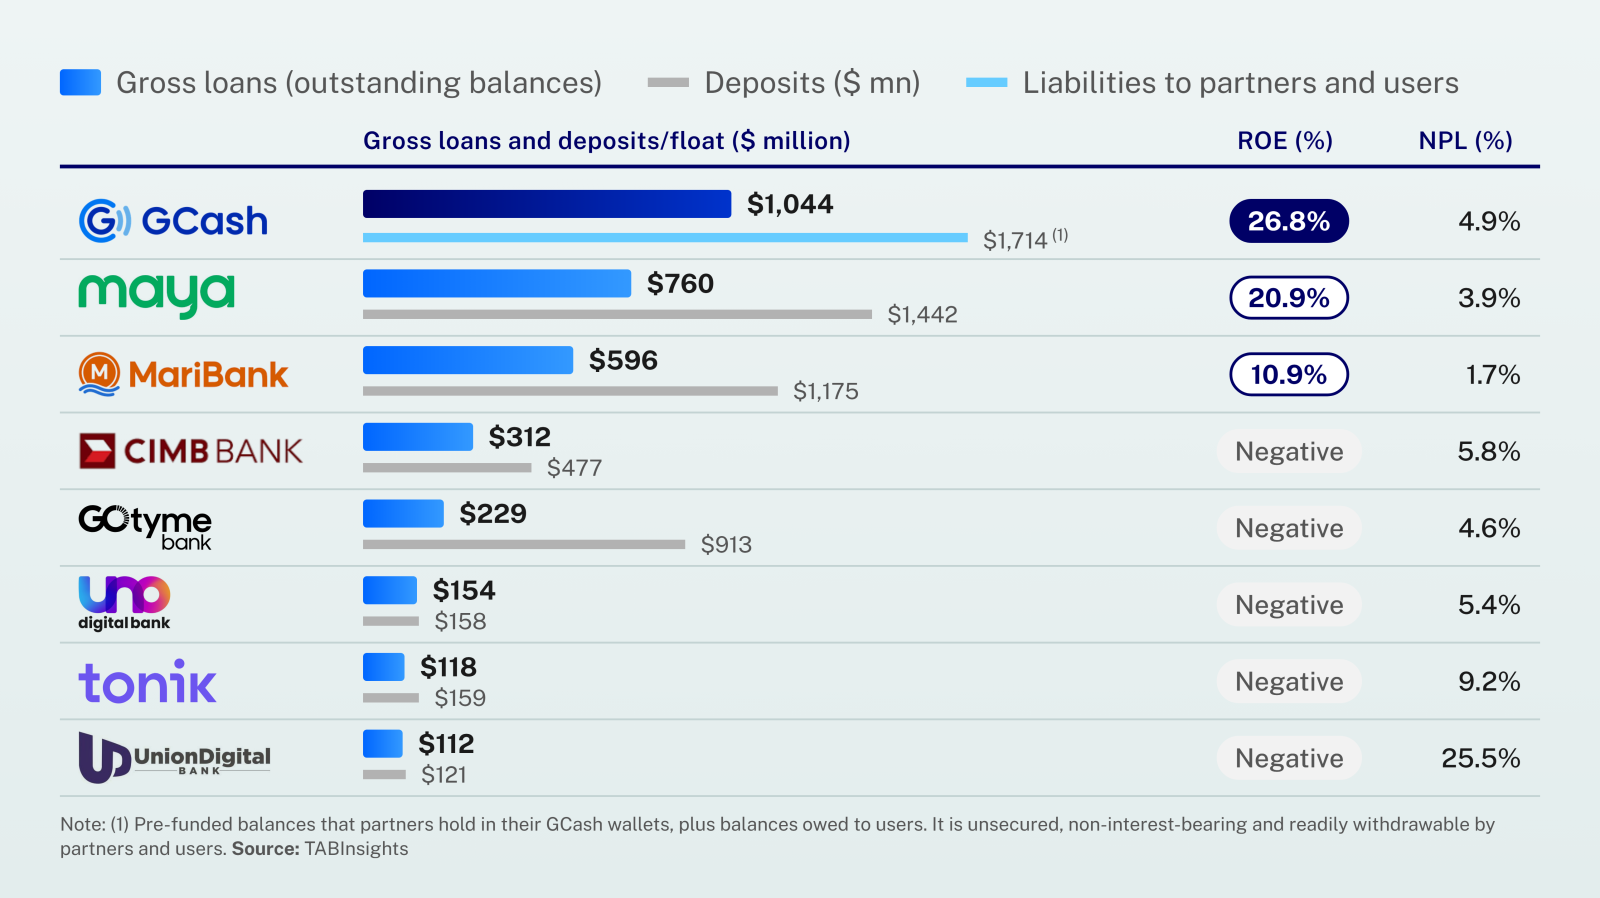
GCash has evolved from a payments platform into a bank-like lender, with a loan book and profitability exceeding those of the Philippines’ licensed digital banks. Lending now drives growth, but rising credit losses pose a growing challenge to profitability. Without a bank’s deposit base or banking regulatory framework, GCash’s model combines competitive advantages with structural risks.

Exclusive benefits are on your way. Subscribe and enjoy the benefits.